Unlock Hidden Cash: How to Recover Your Car’s Lost Value
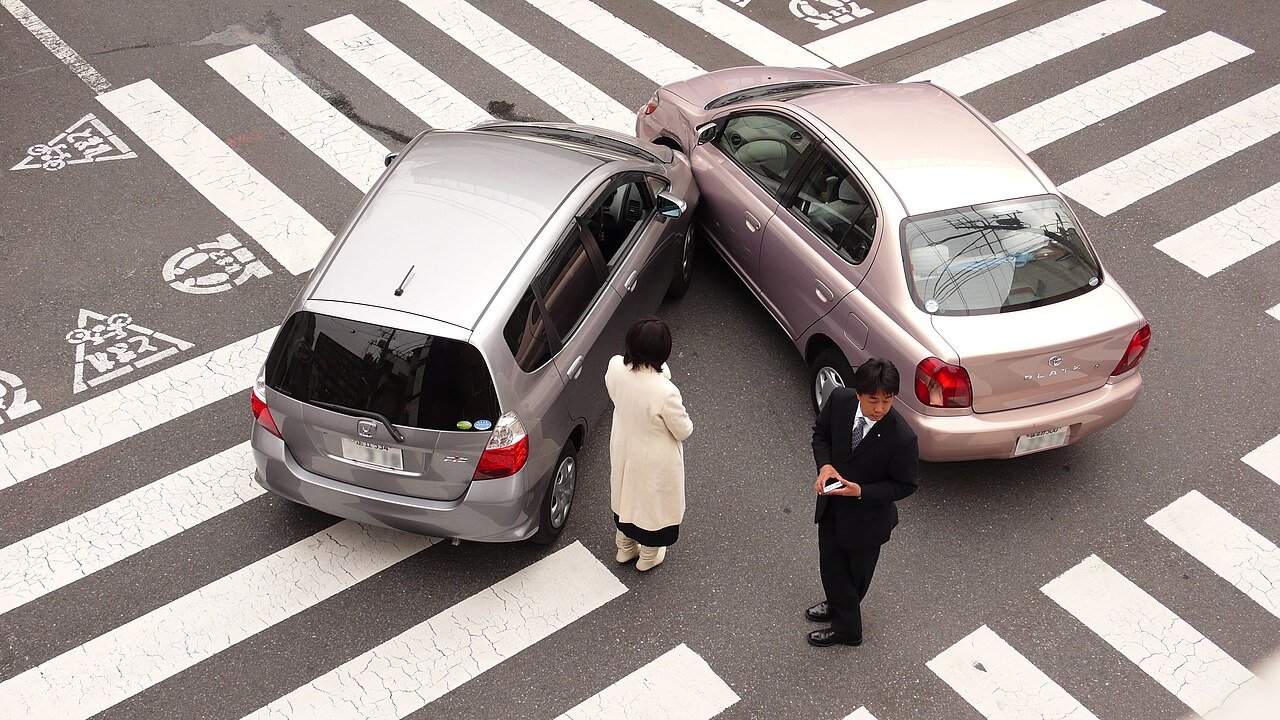
Did you know that even after your car is fully repaired following an accident, its market value has plummeted? Dealerships and private buyers automatically knock down prices for vehicles with accident histories on their Carfax reports. Fortunately, you don’t have to absorb that financial hit. By filing a diminished value claim, you can demand the insurance company pay you the difference between what your car was worth before the crash and what it is worth now.
1. Verify Your Eligibility
Before you start putting together paperwork, you need to confirm that your situation qualifies for a diminished value payout. Insurance rules vary by state, but standard criteria generally include:
- You were not at fault for the accident.
- You live in a state that permits first-party diminished value claims (or you are filing against the at-fault driver’s insurance company).
- Your car is relatively new, a luxury vehicle, or has low mileage.
- The structural frame or major body components were repaired.
2. Obtain an Independent Appraisal
Insurance adjusters will rarely offer a fair diminished value settlement right out of the gate—if they mention it at all. To prove your car’s true loss in market value, skip generic online calculators and hire a certified independent auto appraiser. A professional appraisal report provides concrete data, comparable sales, and undeniable proof of your car’s diminished market worth that insurance companies struggle to dispute.
3. Submit a Formal Demand Letter
Once you have your appraisal report in hand, it is time to write a formal demand letter to the at-fault driver’s insurance adjuster. Your package should include your appraisal, repair invoices, and proof of pre-accident value. Clearly state the exact dollar amount you are demanding and set a reasonable deadline (usually 14 to 30 days) for their formal response.
Key Takeaways
- Always file against the at-fault driver’s insurance for the best chance of a successful payout.
- Never rely on the insurance company’s lowball initial estimate; invest in an independent appraisal.
- Keep meticulous records of all repair invoices, diagnostics, and communication logs.
Frequently Asked Questions
What is a diminished value claim?
A diminished value claim is a request for compensation from an insurance company for the loss in resale value your vehicle suffers after being involved in an accident, even after being fully repaired.
Can I file a diminished value claim if I was at fault?
In most US states, you cannot file a diminished value claim against your own insurance company (first-party) if you caused the accident. You must be the victim of a not-at-fault collision to collect from the other driver’s liability insurance.
How much money can I actually recover?
Payouts vary wildly depending on the severity of the damage, the vehicle’s age, and its make. While minor dings might yield a few hundred dollars, major structural repairs on newer luxury vehicles can result in multi-thousand-dollar payouts.