Understanding the Crisis: Why Insurers Are Targeting Roof Age
Receiving a notice of non-renewal in the mail is a homeowner’s worst nightmare. In the current US insurance market, carriers are tightening their underwriting guidelines aggressively, with roof age becoming the primary culprit for policy cancellations. If your home is 15 to 20 years old, you may have already been flagged by an automated drone survey or satellite imagery, leading your carrier to deem your property a ‘high-risk’ asset. Understanding how to appeal homeowners insurance non-renewal is no longer just a niche skill; it is a critical necessity for maintaining your mortgage compliance and protecting your largest financial investment.
This guide will walk you through the exact steps required to challenge these decisions, negotiate with underwriters, and provide the necessary documentation to prove your roof still has years of life remaining. Whether you are dealing with a major national carrier or a regional mutual company, the process requires precision, patience, and professional advocacy.
Step 1: Verify the Data Behind the Non-Renewal
Before you panic, you must determine if the insurer’s data is accurate. Insurance companies frequently rely on third-party data providers that use satellite imagery or historical permit data to estimate roof age. Often, this data is flawed. Your roof might have been replaced five years ago, but if the permit was never filed or the county database is outdated, the insurance company assumes the roof is original to the home.
How to Challenge Inaccurate Data
- Request the Basis for Non-Renewal: Call your agent immediately and ask for the specific underwriting reason provided by the carrier.
- Gather Evidence: Locate your paid invoices from the roofing contractor, building permits, or even photos taken during the installation.
- Submit a Correction: Send this documentation to your insurance agent as a formal ‘Request for Underwriting Reconsideration.’
If you have proof that the roof is significantly younger than the insurer believes, this is the fastest way to resolve the issue. In many cases, the company will rescind the non-renewal notice within 48 hours of receiving verifiable documentation.
Step 2: Securing a Roof Certification Inspection
If your roof is indeed older—say, 18 or 20 years—you cannot rely on age alone. Instead, you must shift the conversation from ‘age’ to ‘condition.’ An insurance company cares about risk; if a 20-year-old roof is in pristine condition, the risk of a claim is statistically lower than a 10-year-old roof that was installed improperly.
The Role of a Licensed Professional
You need to hire a licensed, reputable roofing contractor to perform a formal roof certification inspection. This is not a standard estimate; it is a technical evaluation of the shingle integrity, flashing, valleys, and ventilation. The contractor should provide a signed, dated report stating that the roof has a remaining useful life of at least three to five years. Providing this document to your insurance underwriter can often override age-based automated guidelines.
Step 3: Negotiating with Your Carrier
When you prepare to appeal homeowners insurance non-renewal, you are essentially entering a negotiation. You are not asking for a favor; you are presenting evidence that you are a low-risk client. If you have been with the company for years and have no prior claims, emphasize your ‘loyalty history.’ Underwriters have the discretion to grant exceptions for long-term policyholders.
Strategies for Successful Negotiation
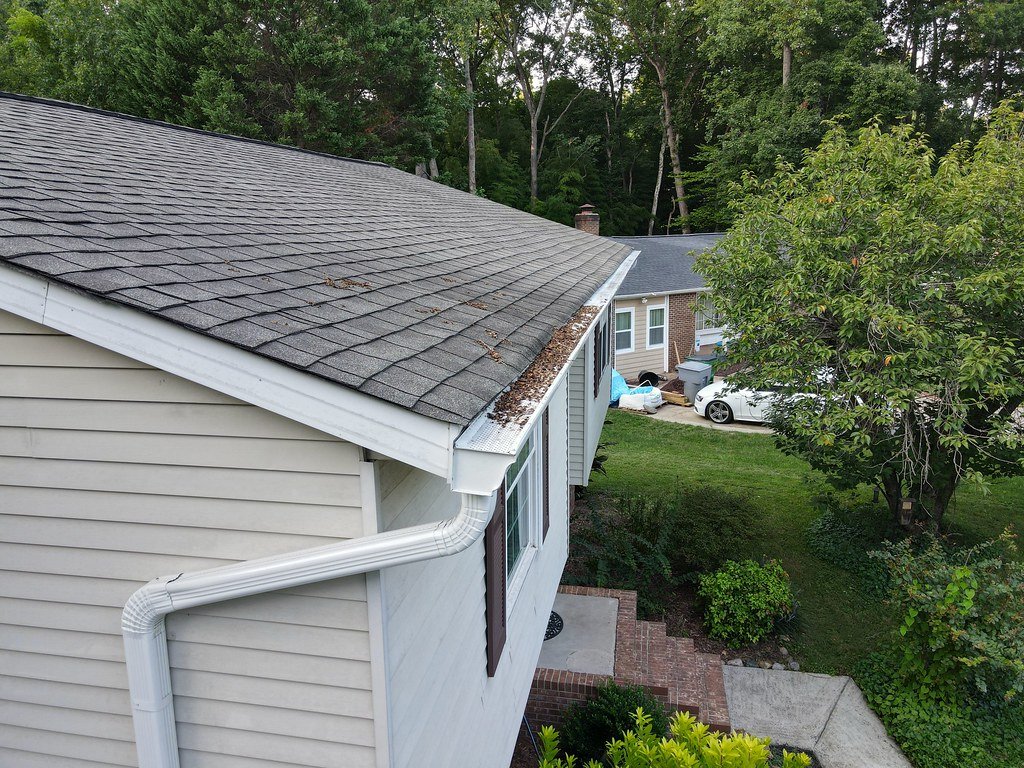
- Highlight Maintenance Records: Show that you have performed regular gutter cleanings and minor repairs.
- Offer a Mitigation Compromise: If the roof is truly failing, offer to replace it within the next 12 months in exchange for a one-year policy extension.
- Escalate to the Manager: If your agent is ineffective, ask to speak with the underwriting department manager directly.
Step 4: Exploring Alternative Coverage Options
Sometimes, despite your best efforts, the carrier will refuse to budge. This is common in high-risk states like Florida, California, or Texas. If the appeal fails, do not let your coverage lapse. A lapse in coverage will make it significantly harder and more expensive to find a new policy in the future.
What to Do If the Appeal Fails
Immediately contact an independent insurance broker. Unlike ‘captive’ agents who only sell for one company (like State Farm or Allstate), independent brokers have access to dozens of carriers, including ‘excess and surplus’ lines that specialize in older homes. They can shop your profile to companies that are more comfortable with aging roofs.
Comparison of Potential Outcomes
| Action Taken | Likely Result | Estimated Cost |
|---|---|---|
| Providing Proof of Newer Roof | Policy Reinstated | $0 (Time only) |
| Roof Certification Report | Possible Approval | $150 – $300 |
| Minor Repairs & Maintenance | Conditional Extension | $500 – $1,500 |
| New Roof Replacement | Full Coverage | $8,000 – $20,000 |
Key Takeaways and Pro Tip
- Never ignore a notice: The clock is ticking. Act within the first 10 days of receiving the letter.
- Use a licensed roofer: Do not use a ‘handyman’ for certification; you need a licensed contractor’s letterhead.
- Keep a paper trail: Every conversation with your agent should be followed up with an email summary.
Expert Pro Tip: If your insurance company flags your roof, ask them specifically if they will accept a ‘Roof Condition Certification’ report. Many homeowners waste money on a basic inspection when the carrier specifically requires a form signed by a licensed professional that explicitly guarantees the roof’s structural integrity for a set number of years.
Frequently Asked Questions
Can I really stop an insurance company from dropping me?
Yes, but it depends on the evidence you provide. Insurance companies are businesses driven by data. If you provide data that contradicts their automated assumptions, they are often willing to reverse a non-renewal decision.
Does a new roof guarantee insurance renewal?
Not necessarily, but it is the strongest factor. If you replace your roof, ensure you provide the final invoice and the permit closure document to your agent immediately to ensure your premium is adjusted and your policy is secured.
What if I cannot afford a new roof right now?
Focus on maintenance. Repairing loose shingles, replacing damaged flashing, and cleaning gutters can extend the life of a roof. A roof certification from a pro can prove to the insurer that the asset is still viable, even if it is older.
Will my rates go up after a successful appeal?
Possibly. Sometimes a carrier will agree to keep you on the books but will increase the premium or raise your wind/hail deductible to offset the perceived risk of an aging roof.
Should I contact my state’s Department of Insurance?
If you believe the insurance company is acting in bad faith or using discriminatory practices, you can file a complaint with your state’s insurance regulator. However, for standard age-based non-renewals, they usually cannot force a private company to write a policy.
Latest News & Current Updates
Stay up to date with recent headlines and market developments related to How to Appeal Homeowners Insurance Non-Renewal Notices Due to Roof Age:
- Australia homeowners get renewal 'bombshells' as 3 in 4 notices offer no reason for hikes — Yahoo Finance (02 Oct 2026)
- Homeowners Insurance Non-Renewal: What to Know — NerdWallet (01 Apr 2026)
- Home insurance drops and denial rates increasing more in Chicago area than national average, experts say — ABC7 Chicago (20 Mar 2026)
- SF homeowner spent $42K to appeal Liberty Mutual's non-renewal but it didn't work. Here's why — ABC7 Bay Area (19 Dec 2024)